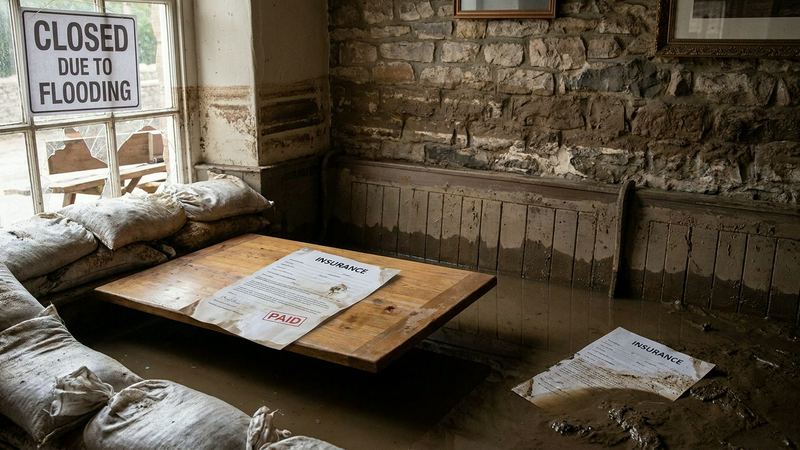
The Restaurant That Was Flooded Twice — and Paid Once
A real cited claim: a restaurant's second flood claim was refused for breach of a flood-resilience warranty. The rule, the arithmetic and what the business could have done.
Each story is drawn from a published court judgment, ombudsman decision or trade-press report, and links through to that source. You can browse them by cover type, by outcome or by the rule that decided the case, and check your own figures against what the claims show using the tools linked from this page.
Explore the business insurance guidesFilter the library by the type of policy involved, how the claim ended, or the specific clause that decided it, whether that's a warranty, an average calculation or a late notification.
A real cited claim: a restaurant's second flood claim was refused for breach of a flood-resilience warranty. The rule, the arithmetic and what the business could have done.
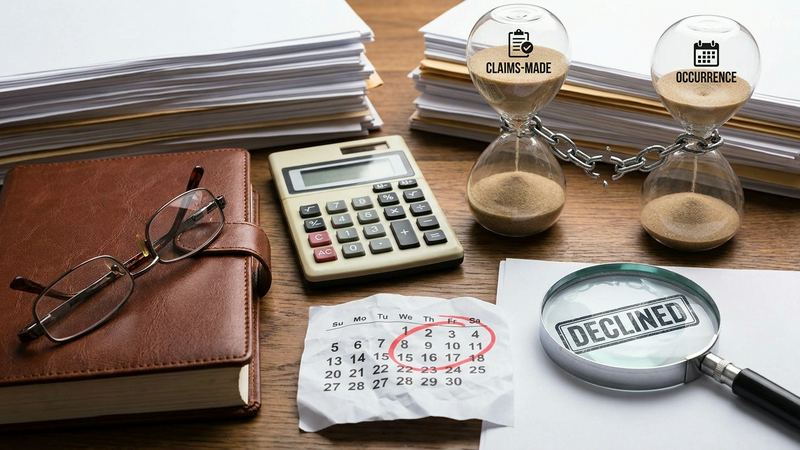
A real cited claim: a professional indemnity insurer declined cover because the accountant notified outside the policy period. Claims-made versus occurrence, explained through the loss.
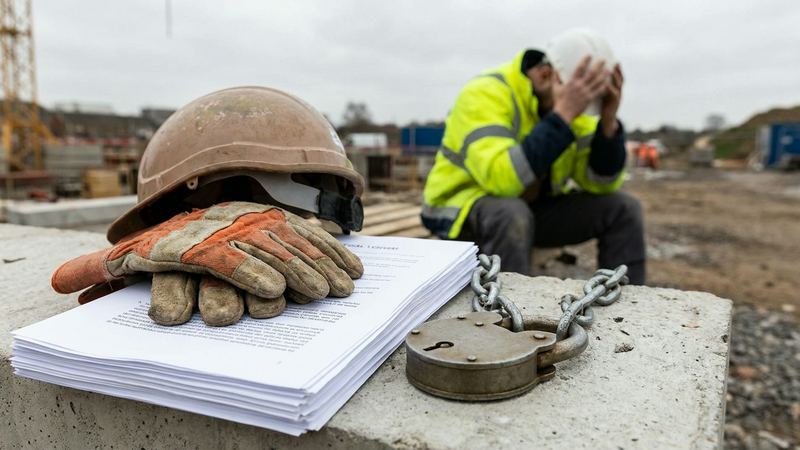
A real cited case: a builder was fined for employing staff without employers' liability cover. The 1969 Act, the £2,500 daily fine and what the injured worker faced instead.
Every major business insurance cover explained through a real claim it paid or refused — employers' liability, public liability, professional indemnity, business interruption, cyber and more.
The other side of the desk: trade classification, rating factors, claims history, loss ratios, appetite and why two quotes for the same business differ — for buyers and junior underwriters.
Describing your business honestly, choosing sums insured, understanding excesses, reading the schedule, and what the Insurance Act 2015 duty of fair presentation means for your quote.
Each story links to the judgment, ombudsman decision or trade-press report behind it, so you can see where the rule came from.